
I develop time series methods for matrix-valued data, with variables observed across units such as countries or sectors. Papers on cointegration and co-movements appear in Economics Letters and Econometrics and Statistics.
I am on the job market for 2026–2027
Job Market Paper
Impulse Response Inference for Matrix Autoregressions
with Alain Hecq and Ines Wilms
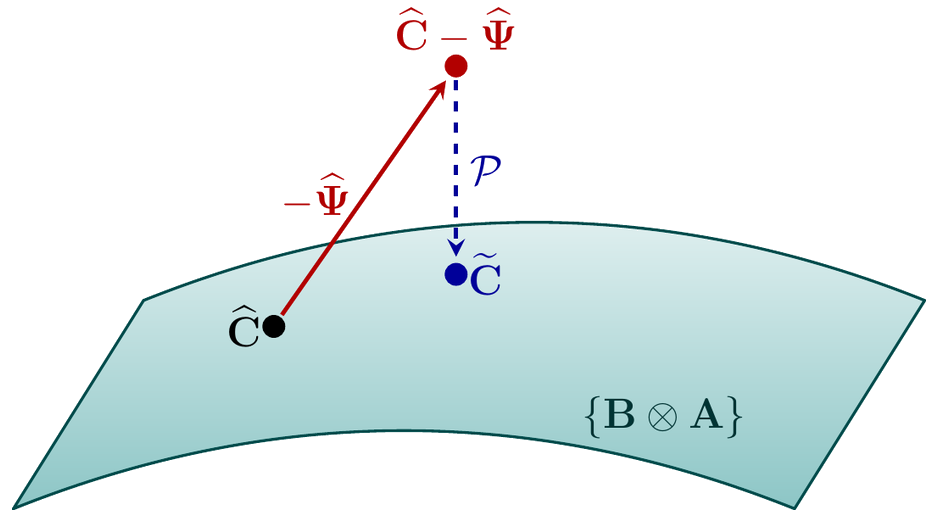
Matrix autoregressions model data such as inflation across countries and categories more parsimoniously than a VAR, but valid inference for their impulse responses has been lacking. We derive delta-method standard errors and propose ProBAB-MAR, a bias-corrected bootstrap with asymptotically correct coverage that delivers narrower intervals than an unrestricted VAR in simulations and an application to Euro-area inflation.
News
Fall 2026 — Visiting Southern Illinois University (host: S. Yaser Samadi).
Oct 2026 — Presenting at the Midwest Econometrics Group, Cincinnati.
Dec 2026 — Presenting at CFE-CMStatistics, Berlin.